Greetings. Happy Valentine's Day.
A few weeks ago
I travelled to a remote village of this country, within the central region. I had
a discussion with a lady who works at a microfinance institution in this
town/village. I gathered some insider information on the economic system in the
rural areas of our country, and why rural women need a “Men’s Conference” of
their own. My source was a credit administrator at the institution.[1]
In Uganda
financial institutions are classified in four tiers; with the top 3 tiers under
the supervision of the Bank of Uganda. The tier IV institutions are made up of
Savings and Credit Societies, Village Loans and Saving Associations, Money
Lenders, plus Microfinance Institutions that don’t keep deposits; they can operate
as they please given the limited regulation covering them and the high level of
risk involved.
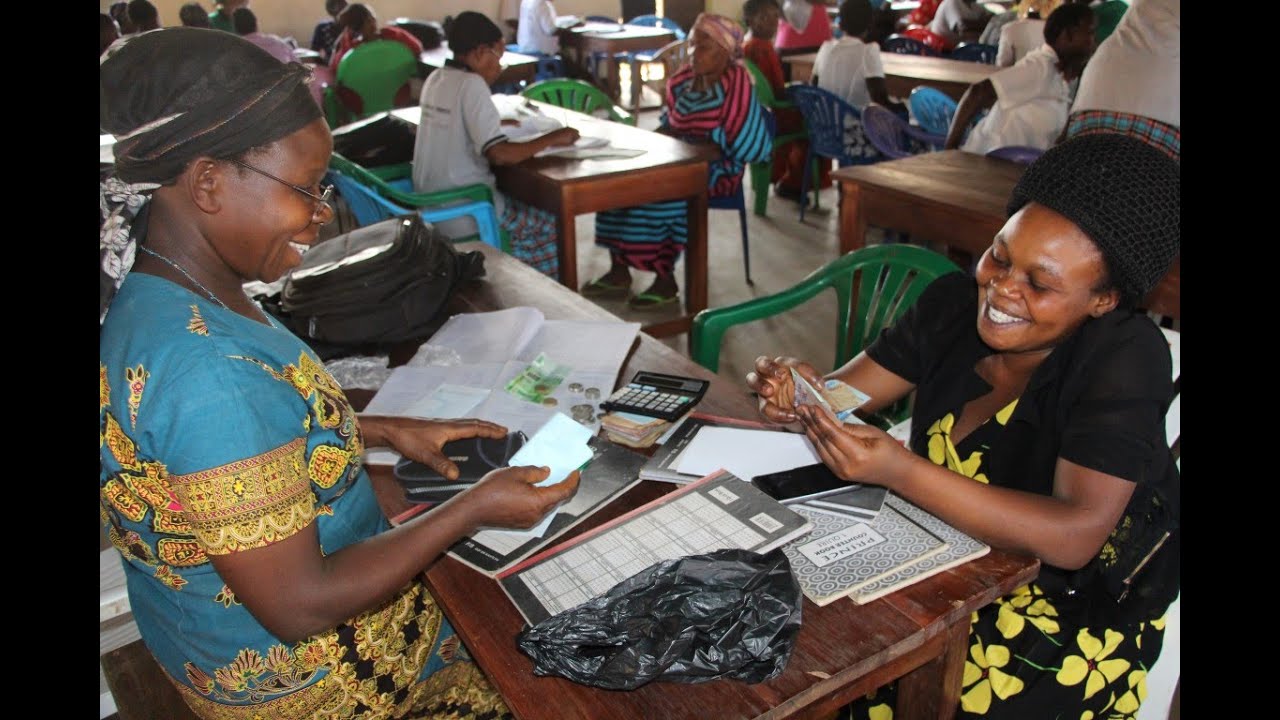
Typically, a
rural setting will possess a tier IV institution. The role of the loans’
officers is to get clients that are in need of credit facilities. This
particular institution focuses on lending to women. These women are arranged in groups, of about 6-10, trained for
about a month on financial literacy and then they are given a lump sum of money
with each taking a portion of about 350,000/=. Each individual member is
responsible for their own portion of the loan.
What do they do with this money?
A portion of
the women start up a business, mostly trading in food stuffs as they earn a
profit from which they’ll spare a portion to repay their loan, which is usually
made on a weekly basis. It all sounds legit, right. Enter the husbands. Olivia
(at least that’s the name I remember), the credit administrator, pointed out to
me that some clients have been driven out of their business premises by their
husbands; the reasons range from how “the activity is embarrassing to the
husband” to “women are supposed to sit at home taking care of the children”. The irony being that this Museveni economy
needs a two-income family to thrive, let alone survive.
There’s a
section of the borrowers who spend their money on their husbands; she takes the
loan, the husband uses it for some ventures that are supposed to be beneficial
to the family. In some cases, this actually works out and the husband does bring
the bread home, as well as contributing to repaying the loan. There are cases
where the husband has used this loan money to marry a second wife! And the
first wife has had to pay back the loan promptly! Bomboclat!
Furthermore,
there are cases where the woman gets the loan for the husband because it will
secure the marriage. The argument goes. In the initial stages, a woman can
qualify for UGX 350,000/= as the maximum amount of money she can borrow. As she
grows in confidence and frequency of borrowing, her limit grows to well over
UGX 2,000,000/=. So, a husband with a woman capable of borrowing above UGX
2,000,000/= has to forego making his relationship official with a maiden who
has just taken her first loan. The opportunity cost on the man is just too high!
Recovering the
loan is not an easy process. In the initial stages of registering potential
borrowers in a group, the microfinance has to record the details of the
borrowers (name, date of birth, national ID number, contact details, etc.). It
is a common phenomenon to find women who do not possess a mobile phone, reason
being “omusajja yangana amasimu” (my
husband does not permit me to possess a phone). So the husband’s number has to
be noted down – only for those who are okay with their husbands knowing that
they are taking a loan. For those that are not, the loan officer has to contact
them through the chairperson of the group. Olivia admitted to me that of her
1,000 members borrowing from her branch, less than 300 have phone numbers! So,
to recover their money, the loan officers are strained when contacting their
clients.
For the
aforementioned group that takes the money to the husbands, loan officers are
forced to humbly go to the husbands and politely ask when the money will be
repayed!
An overlooked solution
On our journey
back, I inquired about the price of land in this town. And I was told one could
get an acre at UGX 2,000,000. So, I and Olivia – my sensei on this journey –
agreed that if a woman borrowed UGX 3,000,000, she could buy an acre of land,
split it into a portion on which to build a residence and the remainder to be
dedicated to agriculture. She can be self-sufficient, earn her own income from
the agricultural side of the land to pay back her loan.
In the long run
she could earn herself a ticket to the “Men’s Conference”; a fictional event
designed to help her avoid the financial expenses her spouse expects on
Valentine’s Day, forgetting she’s been taking care of him throughout the rest
of the year.
Sadly, there are
no happy endings here. Olivia admitted they’ve tried this advice before, and
the women have agreed to take it on; they’ve abandoned it the moment the money
has been disbursed.
Ceteris Paribus
[1] The
name of my source and the microfinance institution shall remain anonymous; I do
not have her permission to share this story.


I didnt the aim of the men's conference till I read this ,now am sad i missed.
ReplyDeleteGreat read
Men's conference, or how to avoid spending during Valentine's Day
DeleteI want that 2million per acre land, who knows what it will cost in a few years 🤫
ReplyDelete... while stocks last!
Delete